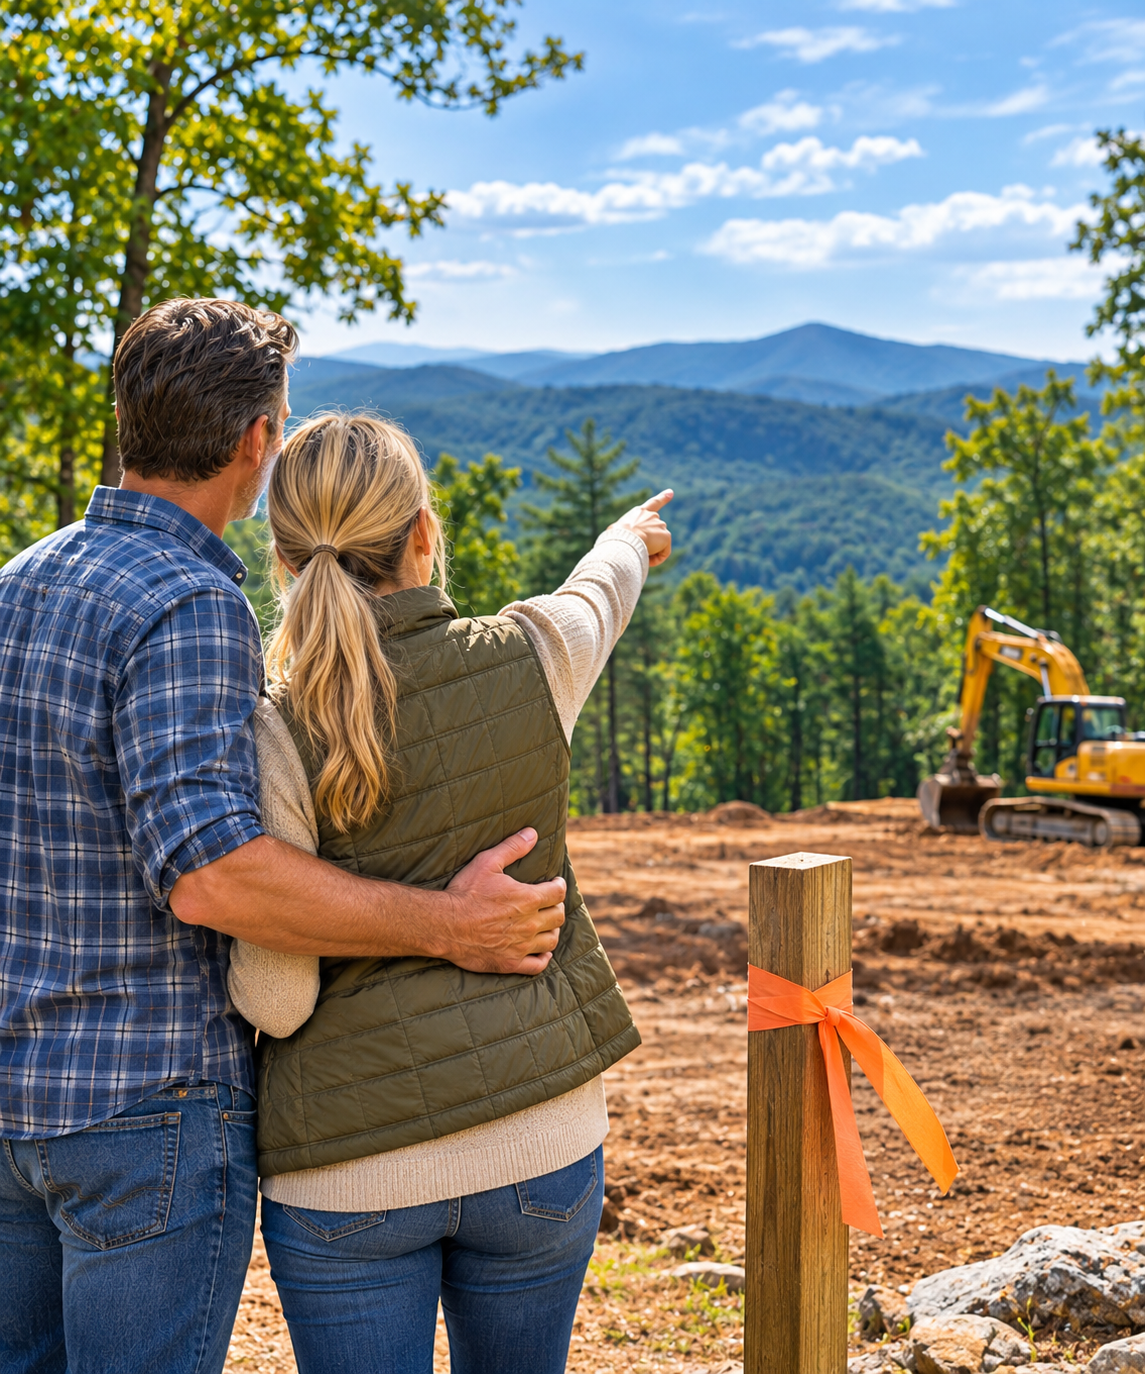
These loans can be especially useful for buyers who have found an ideal location but are not yet ready to begin construction. Depending on the program, borrowers may purchase a lot independently and arrange construction financing later, or coordinate the land purchase with a planned construction project.
Lot financing requirements vary based on the property, lender, intended use, and borrower’s financial qualifications. Alex can help explain the differences between purchasing land separately and combining the lot purchase with future construction financing.
Secure Your Ideal Mountain Property Before You Build
The North Georgia mountains offer a variety of residential land opportunities, including scenic mountain lots, wooded acreage, lake-area properties, and homesites within established developments. Purchasing land before beginning construction can give buyers additional time to plan their future home while securing a desirable location.
A construction lot loan may allow you to purchase property while researching architectural designs, selecting a qualified builder, evaluating site preparation costs, and developing a realistic construction budget. This approach can be particularly attractive when you find a property that meets your needs but are not ready to begin building immediately.
Before purchasing, buyers should investigate zoning restrictions, access, utilities, septic suitability, building setbacks, and any applicable community requirements. These considerations can significantly influence the feasibility and cost of future construction.
Advantages of Financing Land Before Starting Construction
Purchasing a residential lot separately from the homebuilding process can provide flexibility for buyers who prefer to complete their plans in stages. Depending on the available loan program, potential advantages include:
- Purchase Land When Available: Secure an eligible homesite without waiting until every construction detail is finalized.
- Additional Planning Time: Develop house plans, research builders, and establish a construction budget.
- Flexible Financing Structures: Explore available loan terms that may accommodate different construction timelines.
- Potential Land Equity Benefits: Eligible equity in the property may contribute toward future construction loan requirements.
- Coordinated Financial Planning: Prepare for a future construction mortgage while managing the initial land purchase.
- Property Selection Flexibility: Consider eligible lots within residential developments or privately owned acreage.
Loan terms, repayment structures, and future refinancing opportunities depend on lender guidelines. Purchasing a lot does not guarantee approval for a later construction loan.
Who Should Consider a Residential Land Purchase Loan?
Construction lot financing may be suitable for a variety of buyers who want to establish a location for future homeownership. Common situations include:
- Families planning to build a custom primary residence.
- Buyers preparing for a future retirement home in North Georgia.
- Individuals interested in building an eligible mountain vacation property.
- Homeowners who want to purchase land before selling their current residence.
- Buyers seeking a homesite in a particular neighborhood or residential development.
- Property purchasers who need additional time to select a builder and finalize construction plans.
Alex works with prospective borrowers to review their financial goals and discuss whether available lot financing programs may fit their intended property purchase and building timeline.
Construction Lot Loan Qualifications and Property Requirements
Because vacant land generally presents different lending considerations than an existing home, lot loans may have stricter qualification requirements than traditional residential mortgages. Lenders evaluate both the borrower’s financial position and the characteristics of the property being purchased.
Common requirements may include:
- Credit History: A review of credit scores, existing obligations, and overall borrowing history.
- Down Payment: A borrower contribution based on the loan program, property type, and lender requirements.
- Income and Asset Verification: Documentation demonstrating the ability to meet the loan’s repayment obligations.
- Property Appraisal: An assessment of the land’s value and suitability as loan collateral.
- Land Classification: Evaluation of whether the property is an improved residential lot, unimproved land, or raw acreage.
- Access and Utilities: Review of legal access, available utilities, and other property characteristics.
- Future Construction Plans: Some programs may require information about the intended homebuilding schedule.
Minimum credit scores, down payments, loan amounts, and repayment periods vary by program. Not every parcel of vacant land will qualify for residential lot financing.
Understanding Improved Lots, Unimproved Land, and Raw Acreage
One important consideration when financing land is the property’s level of development. An improved lot typically has access to essential infrastructure such as roads and utilities, while unimproved property may require additional preparation before construction can begin.
Raw land may lack established access, utility connections, or other improvements needed for residential development. Financing raw acreage can be more restrictive because lenders must consider additional property risks and development requirements.
Before purchasing land in Blue Ridge or the surrounding mountains, buyers should consult qualified local professionals regarding surveys, soil evaluations, septic permits, water access, and building restrictions. Understanding these details early can help prevent unexpected expenses during the construction process.